
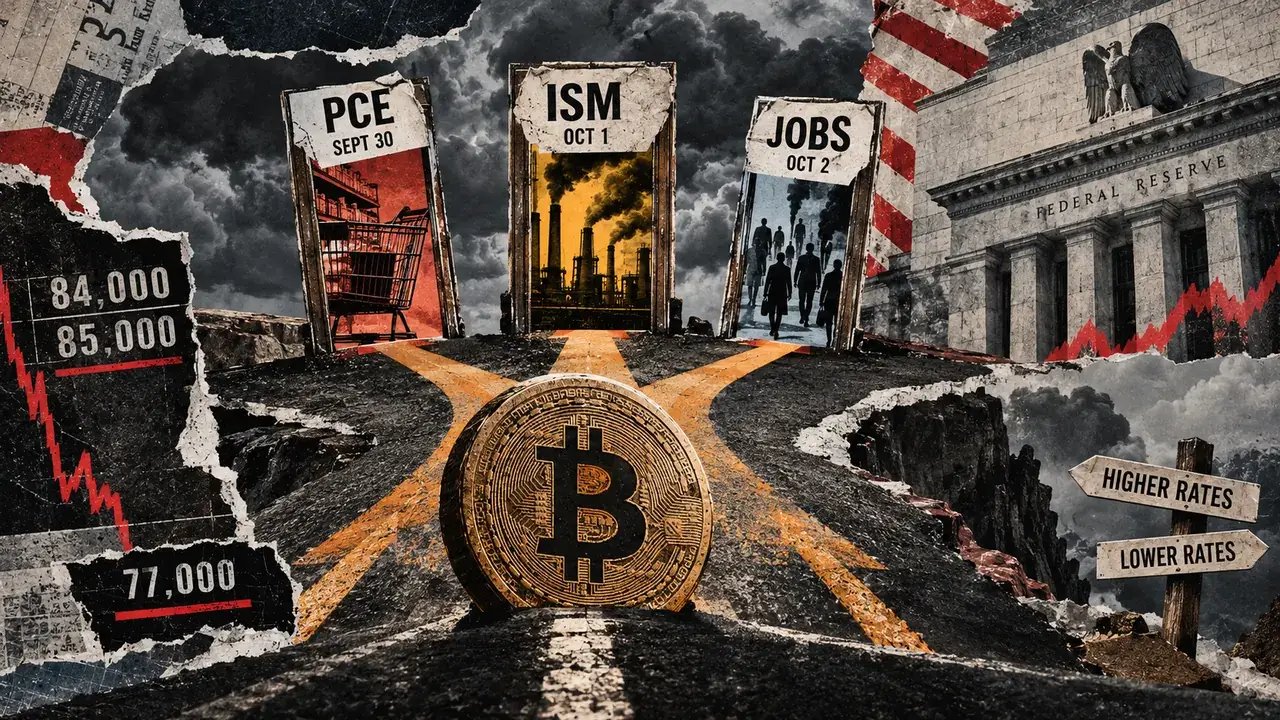
Bitcoin has fallen to an intraday low of $82,563, leaving the cryptocurrency just below a key buying zone identified by Glassnode as Wall Street prepares for three US economic readings that could point in different directions on inflation and interest rates.
The personal income and outlays report, covering August, is due on Sept. 30. It will be followed by the ISM manufacturing survey for September on Oct. 1 and the September employment report on Oct. 2.
The sequence means traders could receive a relatively reassuring consumer inflation reading before seeing less favourable evidence of rising costs faced by manufacturers. Although the reports measure different parts of the economy, each could influence expectations for the Federal Reserve’s next policy decisions.
Glassnode’s analysis on Sept. 23 showed a substantial concentration of long-term holder supply between $84,000 and $85,000. That range represents prices at which many longer-term investors acquired Bitcoin and could provide a clear measure of whether the market can recover as the week’s data emerge.
The analytics firm also placed its deeper True Market Mean reference near $77,000, while its overhead mean MVRV reference stood near $96,700.
A Sept. 21 Glassnode Market Pulse report found net spot taker buying, increasing trading volume and high futures leverage, although weekly exchange-traded fund outflows continued. A recovery supported by new spot buying, stronger volume and ETF demand would be considered more substantial than one driven only by futures positions being closed.
August data may miss later energy shock
The Energy Information Administration estimated that Brent spot crude averaged $91 a barrel in August, $7 higher than in July, as Middle East exports remained restricted.
The International Energy Agency also reported that Gulf diesel and gasoil exports were severely constrained in August, while a physical crude benchmark recorded another sharp increase by Sept. 9. Diesel fuel subsequently reached a nominal record of $6.53.
The Sept. 30 PCE report cannot capture changes in fuel, freight and industrial costs that occurred later in September. The International Maritime Organization recorded damage to vessels in and near Hormuz on Sept. 21 and 23, indicating that shipping risks continued after the period covered by the inflation figures.
JOLTS and PCE describe August conditions, whereas the ISM survey and payrolls will offer the first economic readings for September.
Investors may push Treasury yields and expected Fed rates higher if they believe increased business costs will keep inflation elevated, even before those increases reach consumer prices. A soft August PCE result could temporarily reduce that pressure but would not resolve what happened later.
The ISM’s August report recorded a Prices Index of 71.1 and Supplier Deliveries at 59.3, pointing to slower deliveries. Respondents listed diesel fuel and freight among commodities rising in price, while also raising energy costs and the Hormuz conflict.
A higher September Prices reading, combined with slower deliveries or further comments about costs, would suggest renewed pressure on manufacturers. New orders and employment will help indicate whether demand is surviving those increases.
The Aug. 29 JOLTS release offers an early labour-market signal, while the Oct. 2 payrolls report will provide a more direct test of the economy’s growth outlook. The Fed raised its target range to 3.75% to 4% on Sept. 16, saying inflation remained elevated while job gains had kept pace with the workforce.
Moderate cooling in employment could reduce pressure for higher rates, but a much larger shortfall could revive concerns over economic growth.
The most difficult combination for Bitcoin would be soft August PCE data followed by a higher September ISM Prices reading. An initial rally could then fade if Treasury yields and interest-rate expectations rise again.
Softer PCE, no further increase in ISM costs and moderate job cooling could ease yields. Bitcoin’s move back into the $84,000 to $85,000 holder-cost range would carry greater significance if supported by spot demand.
Persistent inflation combined with resilient hiring could keep rate pressure high, leaving the $77,000 reference in focus if Bitcoin fails to reclaim the holder cluster, without making it a fixed destination.
A severe payrolls disappointment could lower yields but still weigh on Bitcoin if investors respond to a growth shock by reducing risk.
The key issue is whether each release changes yields and Fed expectations, and whether spot buyers support Bitcoin’s response around Glassnode’s dated holder-cost area.


