
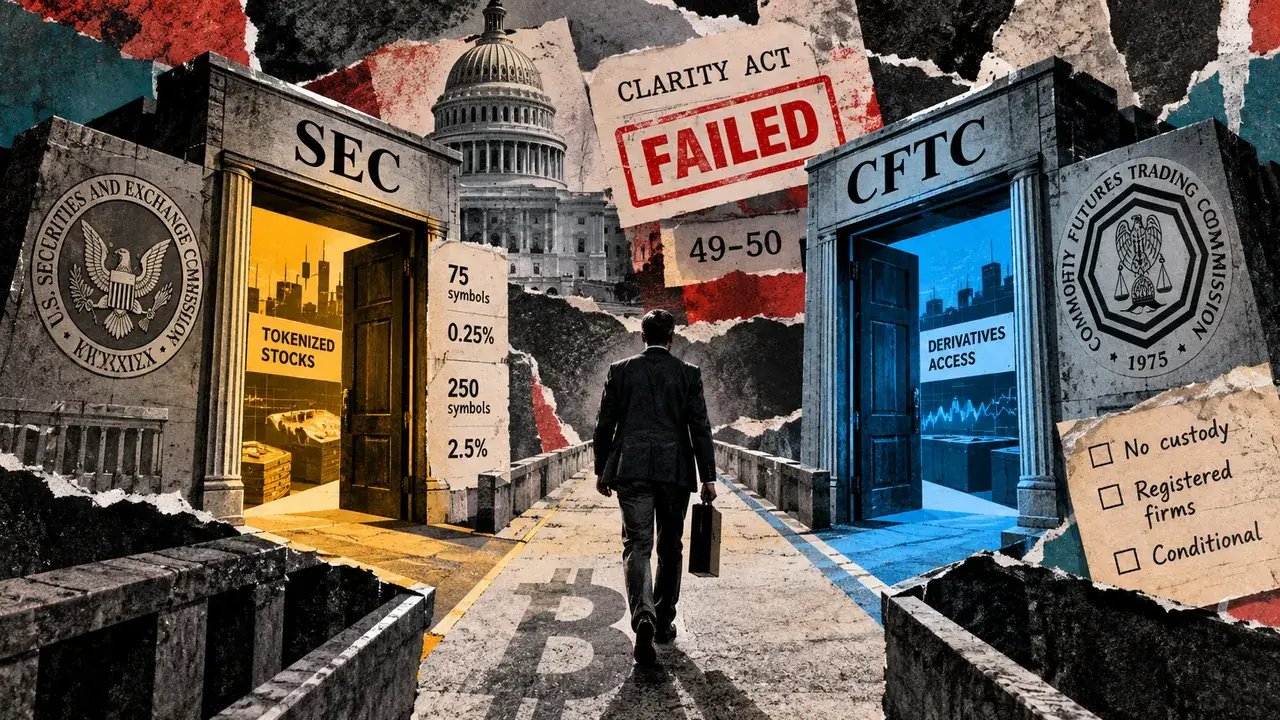
Two US financial regulators have created limited new routes into crypto-linked markets, two days after the Senate failed to advance the CLARITY Act.
The Securities and Exchange Commission (SEC) has authorised a five-year framework for permissioned venues to trade tokenised US shares through automated market makers. The Commodity Futures Trading Commission (CFTC) has widened relief allowing qualifying software providers to connect users with regulated derivatives markets without registering as introducing brokers for the covered activity.
Neither measure creates the broad market structure legislation that failed in Congress. The SEC framework is capped and conditional, while the CFTC approach leaves onboarding, trading and custody with registered derivatives firms and relies on staff guidance that can be changed.
SEC creates five-year tokenised-stock test
Senators voted 49-50 against cloture on 15 September on a motion to proceed to H.R. 3633. The vote was a procedural failure to advance the CLARITY Act, rather than a final judgement on its merits.
On 17 September, SEC Chairman Paul Atkins said the Commission had acted under its existing statutory authority. He described the Innovation Exemption as a bridge towards permanent rules.
The order establishes a Tokenized Securities Venue (TSV). Eligible venues can match buyers and sellers through permissioned automated market-maker pools without being treated as exchanges under the Exchange Act. Some firms supplying tokenised shares from proprietary accounts also receive conditional relief from the dealer definition.
The exemptions last until 17 September 2031 unless changed by the SEC. Across a TSV and its affiliates, Tier 1 shares are limited to 75 symbols and 0.25% of the previous month’s average daily share volume in each stock. Tier 2 shares are limited to 250 symbols and 2.5% of average daily share volume.
Eligible tokens must retain the economic and governance rights of equivalent shares, including dividends and voting rights. Synthetic-exposure tokens, rights, warrants, primary issuances and initial offerings are excluded.
If a third party tokenises a stock, the TSV must notify the issuer and wait at least 30 calendar days. An objection during that period prevents trading on that venue.
Although the underlying blockchain can be public and permissionless, access to the market must be controlled. Venues must verify participants or wallet addresses, publish auditable smart contracts, disclose access restrictions, release transaction data, maintain records, halt trading when the primary exchange suspends the underlying share, report significant system events and disclose operational risks.
Securities Act requirements, anti-fraud and anti-manipulation rules, sanctions obligations, and applicable SEC, self-regulatory organisation and anti-money laundering duties remain in force.
CFTC keeps regulated firms at the centre
The CFTC’s Market Participants Division issued Letter 26-25 on 17 September, extending relief first granted only to Phantom under Letter 26-09 in March. The new position applies to similarly situated passive software providers and is not restricted to crypto wallets.
A qualifying provider can display market and position data, advertise derivatives contracts and registered firms, solicit users, receive revenue-sharing or transaction-based fees, and transmit user instructions. It cannot hold customer assets, produce explicit buy or sell signals, or control order routing or execution.
Users must onboard directly with a designated contract market, futures commission merchant or introducing broker, and must be able to contact that registered firm independently. Collateral remains with a derivatives clearing organisation and/or clearing-member futures commission merchant.
The providers must meet disclosure, marketing, record-keeping and regulatory-notice requirements and share liability with participating registrants for related violations. The letter is not binding on the CFTC, may be modified, suspended or withdrawn, and lasts only until relevant Commission rules or guidance take effect.
The two measures allow controlled launches, but no company is named as committed to use either route. They offer conditional access rather than permanent rights, leaving unresolved the wider division of authority between the SEC and CFTC and the certainty that legislation could provide.


